
UK Property Investment 2026: Is It Profitable for Turkish Investors, and Where to Start?
- Analysis
TBMag Editorial Team
- 0
- 18 minutes read
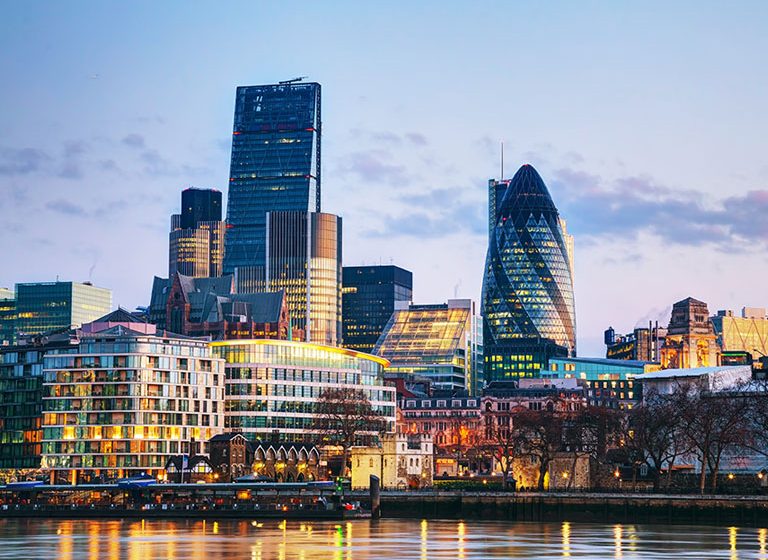
TBMAG Special Report | Investment & Real Estate
Introduction: Two Countries, Two Climates
There is a sentiment the diaspora knows all too well: you save your money, yet your money refuses to wait for you. The economic picture in Turkey over the past few years has become familiar by rote—stubbornly high inflation, suppressed interest rates, a volatile exchange rate, the daily attrition between landlord and tenant, and the quietest, sharpest ache of all: the real return on property slowly eroding against inflation. We have seen this film before. Most of us have seen it more than once.
It is precisely this fatigue that draws the Turkish investor—looking out from London—towards the British market. The answer to “why” lies in the structural divergence between the two nations, and every step taken without grasping that difference risks buying a ticket to the very same sequel.
The figures simplify the matter. According to early 2026 data, the average payback period (amortisation) for a residential property across Turkey stands at 14 years; the average sales price per square metre is 39,843 TL, the average home price is 4.98 million TL, and the average rent is 26,530 TL. In short, at current rental levels, a property takes fourteen years to pay for itself—and even that timeline constantly shifts under inflationary and currency pressures. In the UK, the equation is built upon a wholly different logic: a chronic housing supply deficit, resilient rental demand, and a transparent legal framework. Leading consultancies such as Savills and Knight Frank forecast average capital growth of 18–21% over the five-year period following 2026. Despite short-term fluctuations, sterling-denominated bricks and mortar remain firmly on the table for those seeking to preserve capital.
“First, an honest caveat: Britain is no paradise either. In 2026, house prices have cooled, interest rates are tilting upwards once more, and taxation for overseas landlords is steadily tightening. The objective is not to ‘flee’, but to arrive at the right destination armed with the right intelligence.”
Section 1: Why the UK? Structural Advantages
Legal certainty and title: In England and Wales, conveyancing is conducted from start to finish by a qualified solicitor. Your solicitor examines the Land Registry title, existing charges, local authority planning permissions, and environmental risks to produce a comprehensive Title Report. Unlike the land registry process in Turkey, this provides the buyer with a complete legal X-ray of the asset prior to commitment. It may seem tedious, yet that very tedium is another name for security.
Tenant demand and low void risk: Universities, teaching hospitals, and technology clusters generate steady tenant footfall; major regional cities outside London boast dense student and young professional populations. Whereas sourcing a reliable tenant and collecting rent in Turkey can become a part-time occupation, a rent & legal protection insurance policy in the UK—costing roughly £400–£450 per annum—ensures your rent is paid by the insurer if a tenant defaults, transferring legal eviction proceedings entirely onto the provider. Peace of mind, as they say, has a clear price tag.
Predictable taxation: Aside from Stamp Duty Land Tax (SDLT) paid once upon acquisition, there is no punitive annual wealth-style property tax comparable to Turkey’s system. Should your net rental income fall below the individual personal allowance of £12,570 per year, your UK income tax liability is zero. Furthermore, under the UK–Turkey Double Taxation Convention, tax paid in Britain is not levied a second time in Turkey.
Section 2: Tenure Types — Leasehold vs. Freehold
In Britain, the nature of the title is frequently more decisive than the asking price. Two primary forms of tenure exist:
Freehold: You own both the building and the land it stands upon outright and in perpetuity; this is typical of detached, semi-detached, and terraced houses. There is no ground rent, and you exercise complete control over the property—though full responsibility for structural maintenance and repairs rests solely on your shoulders. Initial entry costs are generally higher.
Leasehold: You acquire the right from the freeholder (landlord) to occupy and use the property for a fixed term; virtually all flats and apartments in England fall under this tenure. Leases are typically granted for 125, 250, or 999 years. Key factors to scrutinise include:
- Unexpired lease term: Properties with leases dropping below roughly 80 years become harder to resell, as mortgage lenders grow reluctant to lend against them. (Good news: ongoing leasehold reforms are softening this “80-year cliff edge”—more on this below.)
- Service charge: Annual estate management, concierge, and communal maintenance fees must be factored directly into your yield calculations.
- Major works: The stealthiest cost item. When a roof or exterior facade requires replacement, the freeholder apportions the total bill among leaseholders. In a 20-flat block, a £200,000 roof refurbishment translates into an unexpected £10,000 bill per flat.
Section 3: Taxes and Upfront Acquisition Costs
The single largest upfront expense is Stamp Duty Land Tax (SDLT). An overseas buyer who already owns residential property—whether in Turkey or elsewhere—faces two additional surcharges:
- Higher Rates for Additional Dwellings (+5%): Applied on top of standard residential rates for second homes and buy-to-let investments.
- Non-UK Resident Surcharge (+2%): Levied on buyers who do not meet UK statutory residency criteria at the time of completion.
With both surcharges combined, the effective SDLT brackets stand as follows:
- Up to £125,000: 7%
- £125,001 – £250,000: 9%
- £250,001 – £925,000: 12%
- £925,001 – £1.5 million: 17%
- Over £1.5 million: 19%
At the upper end of the market, stamp duty alone constitutes a formidable capital outlay; budgets must be structured with these rates layered on top of the purchase price. Ancillary transaction costs typically include solicitor fees (£700–£1,500), RICS building surveys (£500–£1,000), mortgage arrangement fees (variable), and foreign exchange transfer spreads.
Section 4: Regional Selection — Prestige or Yield?
High-net-worth investors prioritising global prestige gravitate towards London; yield-focused professionals targeting stronger cash flow and capital appreciation look towards the North and the Midlands.
London: Average property prices hover around £700,000, climbing substantially higher across Prime Central London (Kensington, Chelsea, Westminster). Yet London’s prime tier faces headwinds in 2026: according to LonRes data, annual sales prices fell by 7.5% across Prime London and by 9% in Prime Central—marking the steepest contraction since 2009. While central postcodes yield roughly 3% gross, outer zones along key transport corridors can achieve 6–7%. London remains a robust long-term store of wealth, provided buyers can stomach near-term volatility.
Manchester & Salford: The beating heart of the “Northern Powerhouse” stands out for its expanding young professional demographic. Gross rental yields sit comfortably in the 6–8% bracket, with entry-level investment flats accessible between £200,000 and £300,000.
Birmingham: Anchored by the HS2 high-speed rail project and the £10 billion regeneration around Curzon Street, Birmingham continues to draw strong tenant demand. Average rents rose by ~3.3% annually in spring 2026 to reach £1,086 per month. While headline ticket prices are generally lower than Manchester’s, the price-per-square-foot gap is narrower than many assume; underwrite based on hard metrics rather than marketing brochures.
Liverpool & Leeds: Low capital entry points combined with large student and young graduate cohorts deliver reliable net cash flow. In Liverpool, vetting developer track records is essential—here, haste can prove the most expensive advisor.
Section 5: Turkey vs. The UK
| Criterion | Turkey | United Kingdom |
|---|---|---|
| Average Rental Yield | 4–6% (risk of inflationary erosion) | 3.5–7% (sterling-denominated) |
| Payback Period | ~14 years | 12–20 years (region dependent) |
| Inflation Hedge | Weak (TRY depreciation) | Strong (GBP hard currency) |
| Legal Certainty | Variable | High / Standardised |
| Tenant Default Risk | High | Low (insurance readily available) |
If you are purely yield-driven, do not confine yourself to London: acquiring two one-bedroom apartments in northern cities for £150,000–£250,000 apiece will generate substantially higher combined rental income than a single £500,000 flat in the capital. By appointing a regulated UK property management agency, investors based in Turkey can run an entirely hands-off, passive portfolio.
A crucial caveat on residency and visas: Purchasing real estate in the UK confers zero right to residency, settlement, or citizenship. Moreover, the Ankara Agreement (ECAA) route historically favoured by Turkish entrepreneurs closed to new applicants at the end of 2020 following Brexit; today, relocation requires qualifying under points-based routes such as the Skilled Worker or Global Talent visas. Property acquisition serves as an effective wealth-preservation pillar for those already settled legally—not as a key to open the border.
Section 6: The 2026 Interest Rate and Policy Climate
Making an investment decision in Britain today requires stepping onto two shifting surfaces simultaneously: monetary policy and fiscal reform.
Interest Rates: On 17 September 2026, the Bank of England held the Base Rate steady at 3.75%—its sixth consecutive hold, though decided on a split 6–3 vote with three Monetary Policy Committee members voting for an immediate hike. The driver is clear: CPI inflation climbed to 3.1% in August, propelled largely by energy prices amid the Iran conflict. The Bank projects inflation to rise further in the coming quarters, potentially breaching 4% in early 2027. Consequently, the summer mortgage rate-cutting war among high-street lenders has abruptly halted; markets are now pricing in a potential rate hike, viewing the 5 November meeting as “live”. Two- and five-year fixed mortgage rates sit around 5.5% and are edging upwards. The takeaway for buyers is straightforward: run your numbers at today’s borrowing costs, not on the wishful expectation of imminent rate cuts.
Politics and Tax Policy: Here, noise abounds while hard legislation is narrower—separating the two is an investor’s most profitable skill. Andy Burnham, who took office as Prime Minister on 20 July 2026, has long been associated with proposals to scrap Stamp Duty in favour of a land value tax or proportional property tax (such as Fairer Share’s 0.48% model). Yet in his inaugural interview as Prime Minister, Burnham took such sweeping changes off the table “for now”: neither SDLT nor Council Tax will be overhauled in this year’s budget. Radical structural reform remains a political aspiration rather than statute—and because it requires a nationwide valuation exercise, most analysts push it beyond the next general election.
What is legislated and directly relevant to investors includes:
- 0% VAT on Domestic Electricity: Effective 1 October 2026 for six months, VAT on household electricity drops from 5% to 0% as part of Burnham’s cost-of-living package.
- The “Mansion Tax”: Announced in Rachel Reeves’s November 2025 Budget, the High-Value Residential Surcharge takes effect from April 2028 on properties valued at £2 million and above, levying an annual charge of £2,500–£7,500. (Press reports suggesting the threshold could be lowered to £1.5 million remain speculative.)
- Higher Income Tax on Rental Profits: Taking effect on 6 April 2027, an increase enacted prior to the Burnham premiership that will directly trim net landlord margins.
And the one line item to watch closely: should a proportional property tax ever materialise, the proposed framework doubles the rate to 0.96% for second homes, empty properties, and overseas-owned residences. For investors buying from Turkey, that is the clause to bookmark ahead of the 2026 Autumn Budget.
As Cem Ekingen of London-based consultancy EKINOX Real Estate observes, short-term market hesitation stems less from policy itself than from policy rumour; the disciplined approach is to stress-test every acquisition against today’s actual numbers rather than newspaper headlines.
Section 7: Step-by-Step Acquisition Process
The transaction is managed end-to-end through your appointed solicitor:
- Budget & Financing: Determine whether you are purchasing in cash or via an international buy-to-let mortgage. Overseas Turkish buyers are typically required to provide a 25–40% deposit.
- Making an Offer: Once a property is selected through regional analysis, a formal written offer is submitted via the estate agent; upon acceptance, the property is marked under offer.
- Conveyancing: Your solicitor conducts title checks, reviews lease terms, and runs local authority and environmental searches.
- Exchange of Contracts: Both parties’ solicitors formally exchange signed contracts; a 10% deposit is usually transferred, making the transaction legally binding.
- Completion: The remaining balance is settled, keys are released, ownership is registered with HM Land Registry, and SDLT is filed and paid within 14 days.
Section 8: 2026 Reforms and the Horizon
The government’s Home Buying and Selling Reform Roadmap, published in June 2026, aims to make transactions faster, digital, and more transparent through upfront Sales Packs, a digital Property Logbook for every home, binding conditional contracts to curb fall-throughs, and phased regulation of estate agents.
Meanwhile, the Leasehold and Freehold Reform Act 2024 is reshaping tenure dynamics: commonhold is set to become the default tenure for new flats, ground rents are being progressively capped, and lease extensions are becoming simpler with a statutory right to extend up to 990 years. For leasehold investors, this promises fewer medium-term surprises—though distinguishing between “enacted law” and “commencement dates” remains vital.
Conclusion: A Smart Asset Class — Not a Magic Escape
When approached with the right location, the right tenure, and an honest advisory team, UK real estate remains a compelling, long-term asset class for Turkish investors. Yet success depends on looking past the headline price. In summary:
- For leasehold properties, scrutinise service charge accounts, ground rent clauses, and major works histories.
- For freehold houses, focus on structural condition and local regeneration fundamentals.
- Clarify your objective: personal residence, net rental yield, or long-term capital growth?
- Factor in taxation early: seek specialist advice on SDLT surcharges, rental income tax, and the 2028 mansion tax.
- Look beyond London: Manchester, Birmingham, Liverpool, and Leeds offer an attractive balance of lower entry costs and resilient yields.
A sterling-denominated property can shield your savings from the quiet erosion of inflation; that much is undeniable. Yet no title deed can ever settle that lingering, unspoken reckoning a person carries with their homeland—nor would it be fair to ask it to. The right postcode, the right tenure, a trustworthy advisor, and a disciplined budget. The rest is what every sound investment demands: a measure of patience, and the quiet caution earned from having seen this film once too often.
THE TBMAG WEEKLY
Stay Ahead of the UK–Türkiye Business Corridor
Weekly insights on business, healthcare, investment and culture — delivered every Thursday. Available in English and Turkish.
No spam · Unsubscribe anytime
